Flood Insurance: What Berkshire County Homebuyers & Homeowners Need to Know
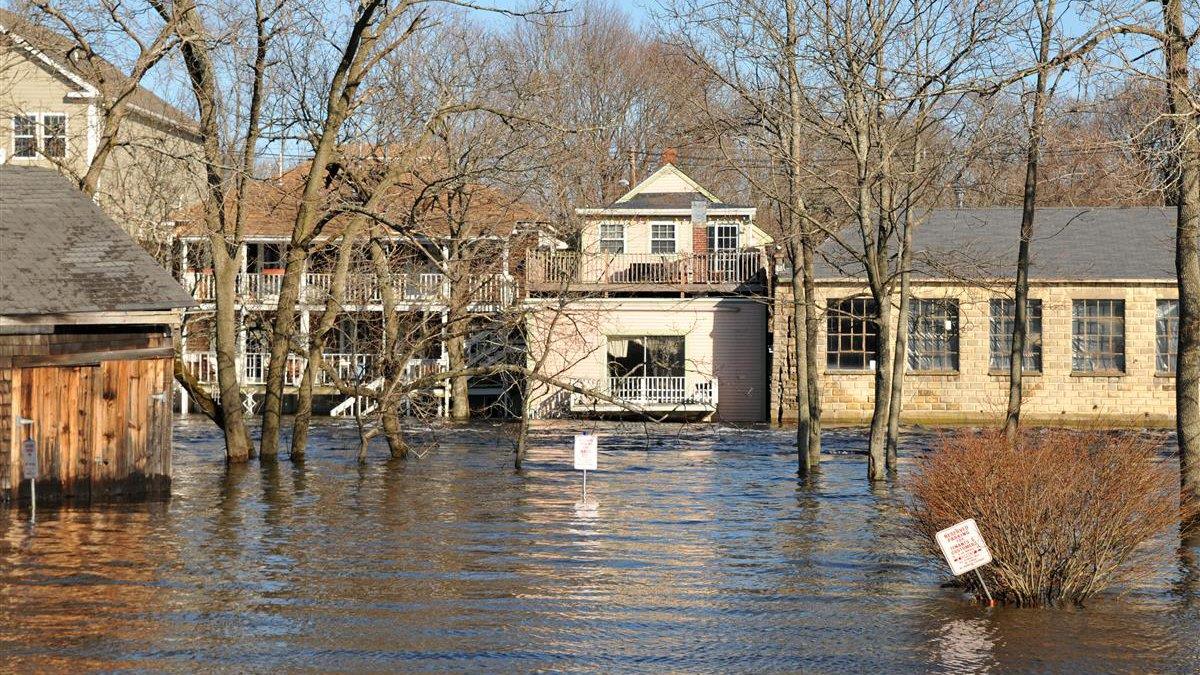
While we love our rivers, lakes and waterfalls here in the Berkshires, they do make us much more susceptible to flood from heavy rains, ice jams, snowmelt, and more. Whether you own or are planning to buy a home, it's equally imperative that you understand property flood risks, your coverage options, and how to protect yourself and your loved ones from a flood catastrophe.
Sharon MacEachern, AVP, operations manager for Greylock Insurance, a Berkshire County based neighborhood agency, reminds us that the unexpected can happen anytime, anywhere.
"In the past decade we've witnessed the devastating effects of two major storm systems, Hurricane Katrina and, closer to home, Superstorm Sandy," says MacEachern. "And we saw how damaging the resulting floods were to families, homes, neighborhoods and businesses, particularly in areas where there was little to no preparation."
One of the least prepared entities was our National Flood Insurance Program (NFIP), which was financially drained by the long, slow, and significant recovery necessary to rebuild after these storms. Together, Katrina and Sandy left the NFIP drowning in $20 billion of debt. This enormous debt has had a serious and direct impact on homeowners who live in neighborhoods by the water, as well as potential buyers of these homes.
Starting with the Biggert-Waters Act of 2012 (or BW-12), the federal government has enacted programs to try to lower the NFIP's debt. However, the only major impact of new regulations has been to dramatically hike up flood insurance rates for policyholders in flood zones, particularly those in coastal areas, freezing the real estate markets in these areas.
There was also a perceptible slow-down in real estate activity in non-coastal areas like the Berkshires. The uncertainty around potential increases in flood premiums across the nation kept potential homebuyers away from river and lakefront properties and caused many current homeowners – maybe even yourself – to delay putting a home on the market.
To allay the fears of both homebuyers and homeowners, the government enacted the Homeowner Flood Insurance Affordability Act of 2014 (or HFIAA), which rescinded or delayed many of the BW-12 rate increases. HFIAA still caused a flood of problems, however, when it increased the surcharge on secondary homes by $250. More reforms have followed, but none seem to have reversed the course of the NFIP's debt or the uncertainty of the flood insurance market.
"There is a light up ahead for the flood insurance market though," MacEachern says. "As often happens, adversity is the father of invention. We have seen several private insurers start to enter the flood insurance market and they are delivering more cost-effective options to customers."
Here are some interesting examples of this private insurers movement:
- Lloyd's of London has many syndicates now writing individually risk-rated flood insurance at premiums substantially lower than the (NFIP). And with expanded definitions of flood, the ability to carry higher deductibles and contracts meeting the lenders' requirements for flood insurance, they are starting to gain popularity.
- Philadelphia Insurance Companies, in an unprecedented move, started to write Commercial Flood insurance as part of a package in favorable flood zones about 3 years ago. Like Lloyd's, their coverage is much broader than the NFIP.
How much could flood insurance through a private insurer save you? Sharon gave us some real-life anecdotes that demonstrate that customers have everything to gain by looking into this option:
-
- Customer A had an NFIP Policy with $159,000 in coverage and a $2,000 deductible for $3,214 a year. Greylock Insurance placed the policy with Lloyd's and got the customer $219,000 in coverage with a $5,000 deductible for $855 a year. That's a $2,359 savings/year.
- Customer B had an NFIP Policy with $107,500 in coverage and a $5,000 deductible for $1,938 a year. Greylock Insurance placed the policy with Lloyd's and got the customer $180,000 in coverage with a $5,000 deductible at $720 a year. That's a $1,218 savings/year.
Private insurer stories like these are causing the federal government to take notice. Hearings in Washington at the beginning of the year included conversations about the role that the private market could play in helping find a flood insurance marketplace solution.
"There's no time like the present," says MacEachern. "The current NFIP plan is due to expire in September of 2017, and it's time for all interested parties to come together to formulate a plan."
Most industry participants support a balance between the private insurance market and the availability of coverage through NFIP in order to weather the long-term risk of floods and lessen the impact of disasters such as Hurricane Katrina and Superstorm Sandy.
While there is still uncertainty, MacEachern believes that positive changes are coming for homeowners in flood zones and homebuyers who desire a coastal, riverfront or lakeside home.
"One thing for certain is that Berkshire homeowners should understand their flood risk, their coverage options, and how to protect themselves and loved ones from a flood catastrophe," she says. "As Berkshire's neighborhood insurance agency, Greylock Insurance is particularly suited to guide you through your community's rating system and help you complete the required forms to get coverage for your home and its contents. We will gladly help you navigate the complicated waters of this complex industry."
For assistance or a free quote, please call 888-200-4445.



